WHERE TO INVEST: Is it time for a closer look at Nedbank?
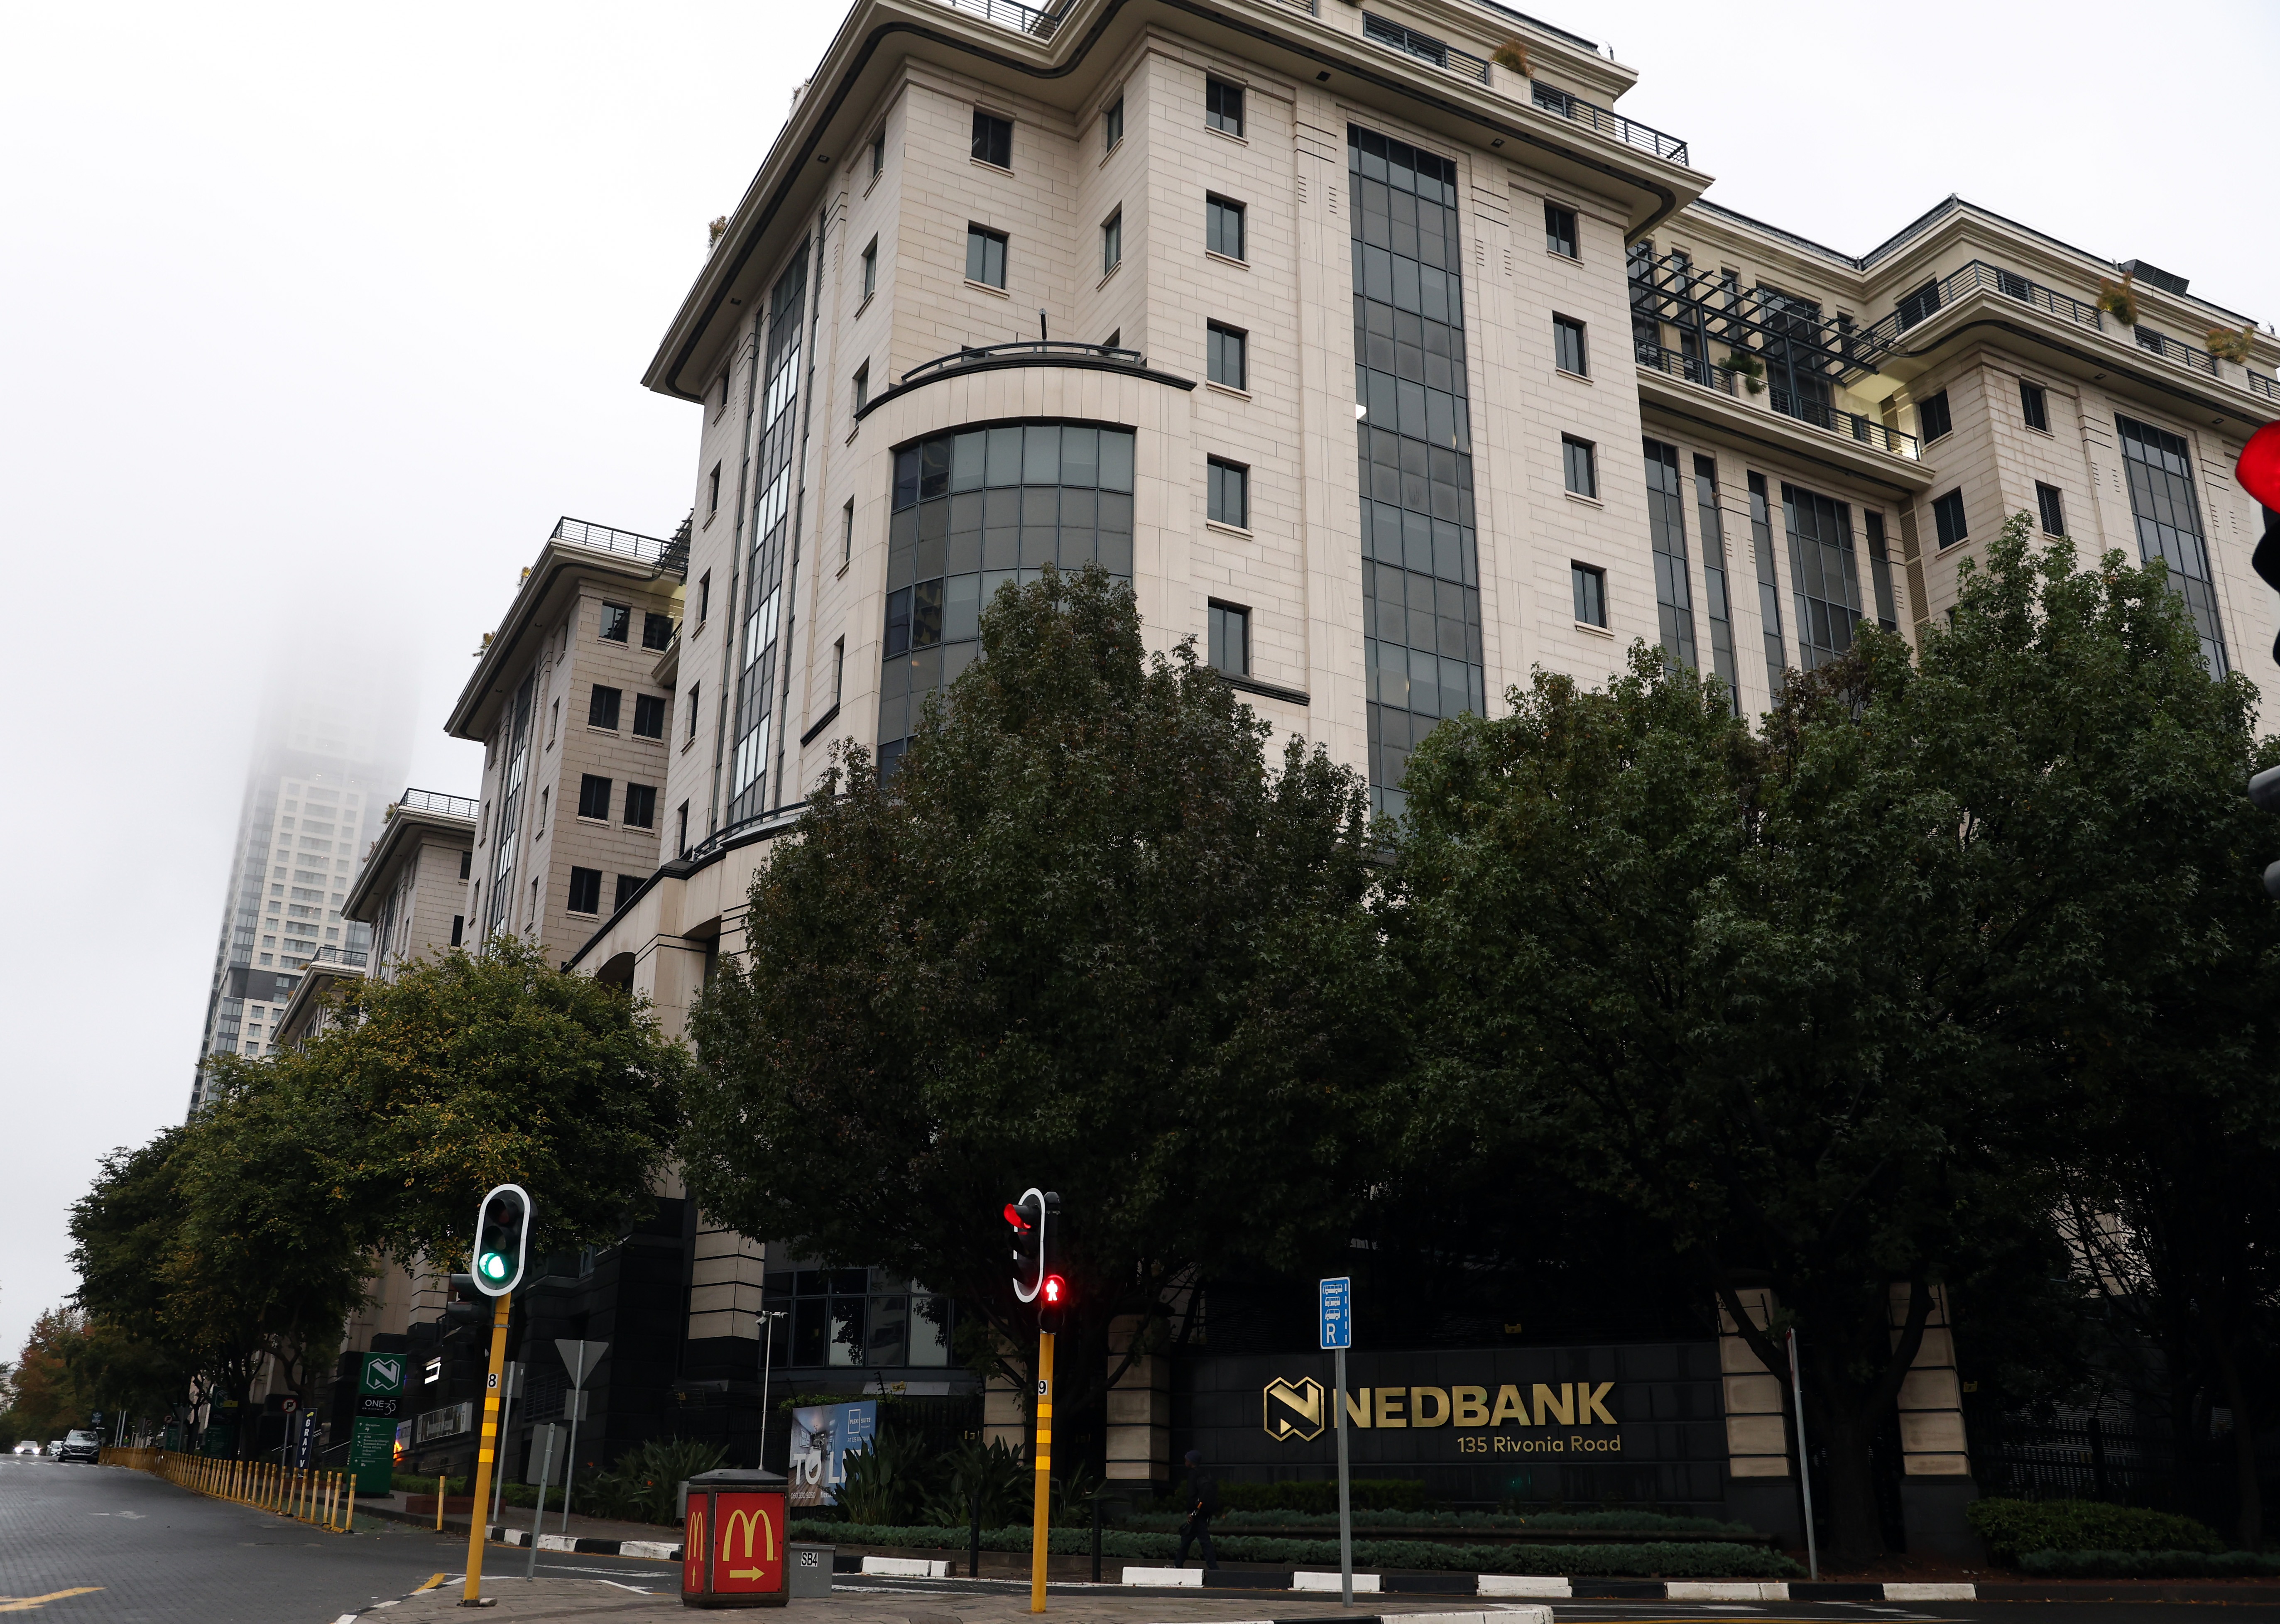
South Africa is known for many things, and one of the more positive ones is the state of our banking sector. We have a highly regulated, world-class banking system that boasts a mix of traditional banks and impressive disruptors. We have groups that have successfully diversified beyond our borders. In fact, if the entire country could run as effectively as our financial services infrastructure, this place would have completely different economic growth.
With rare exceptions (like Capitec and its all-conquering track record in winning market share), the performance of banks is tied closely to the broader, macroeconomic story. As sentiment has improved in South Africa and on the broader continent over the past 12 months, so our banks have performed well.
Capitec has delivered a total return of 38%, driven by their excellent ongoing strategic execution. But we’ve also seen a couple of the legacy banks making up some lost ground, with Absa returning 61% over 12 months and Standard Bank good for 55% (both on a total return basis).
FirstRand’s 38% total return is exceptional in the context of that group’s problems in the UK market. The Financial Conduct Authority motor redress scheme has ended up being vastly more expensive than anyone could have imagined, leading to FirstRand’s decision to exit the UK market entirely. The share price would have done even better in the absence of that mess.
Then we find Nedbank with a total return of “only” 26% in the past 12 months. That’s great when viewed in isolation, but it looks pedestrian compared with sector peers.
With Nedbank as the clear laggard, it begs the question: is there value here, or is Nedbank a value trap that investors should avoid?
The price/book multiple is a helpful place to start, since this is the industry-standard valuation multiple for banks. The reason is simple: banks carry almost all their assets and liabilities at fair value, so the net asset value (or book value) is a decent approximation of what the equity in the group might be worth if they stopped operating.
But of course, these businesses are going concerns (i.e. they plan to keep operating), so the market pays either a discount or a premium to book depending on the profits generated by the balance sheet (measured by return on equity) and the growth prospects.
Nedbank is trading on a price/book of 1.1x (i.e. a slight premium to NAV). This is slightly behind arch-rival Absa (1.18x), and in a different postal code to Standard Bank (2.0x) and FirstRand (2.45x). Capitec operates in its own universe entirely, with a price/book of 9.1x!
Price/earnings (P/E) multiples may be more familiar to you, with Nedbank on just 7.4x vs Absa at 8.2x. FirstRand’s earnings have been skewed terribly by the UK situation, so it’s better to compare these multiples with Standard Bank (10.8x) and Capitec (a whopping 32.1x).
Clearly, the market believes that there are still many great things to come from Capitec. As for FirstRand and Standard Bank, they enjoy a premium valuation based on their scale and return on equity characteristics. Nedbank and Absa are left to fight over the breadcrumbs of investor attention, the unfortunate result of years of relative underperformance vs their peers.
Nobody would argue that Nedbank is a better bank than Capitec, or even Standard Bank. The argument is whether Nedbank is good enough at this modest multiple. A decent pre-close update by Nedbank suggests that there might be value here after all.
Single-digit income growth is the order of the day at Nedbank. This doesn’t leave much room for error in the credit loss ratio or in growth in expenses, so Nedbank has to run a tight ship just to generate reasonable growth in earnings.
In the five months to May, being the first five months of Nedbank’s financial year, they achieved net interest income (NII) growth of low- to mid-single digits. Asset growth was higher, but pressure on net interest margin led to this rather uninspiring outcome. Thankfully, non-interest revenue was in the upper-single digits, which is a lot better.
The credit loss ratio isn’t cooperating at present, sitting in the upper half of the through-the-cycle range. A significant default in the business and commercial banking cluster was an unpleasant surprise for investors.
On the plus side, expense growth was excellent, coming in below mid-single digits. They expect this to continue for the rest of FY26, suggesting that they might even achieve an uptick in margins if the credit loss ratio behaves itself.
Once everything else is considered (including the lack of associate income after the sale of Ecobank), we find that headline earnings grew by upper-single digits.
That’s about as good as anyone can realistically expect from Nedbank, especially as their exposure to Africa (a high-growth region) is limited. They are still in the process of finalising the important NCBA deal in Kenya, hopefully in time to take advantage of the favourable cycle in the region.
But the real question is: how does this performance compare to the valuation?
An old rule of thumb in investing is to seek out companies with a PEG ratio of 1 or lower. This is calculated as the P/E multiple divided by the growth rate e.g. a P/E of 7x and a growth rate of 7% is a PEG of 1. Based on this Nedbank update, they are trading on a PEG of roughly 1, with investors enjoying a trailing dividend yield of 7.9%.
Goodness knows they are facing a lot of disruptive forces, but Nedbank is worth a closer look at this price. Nobody is expecting them to be great. The hope is that they are merely good enough – a far less demanding hurdle than you’ll find at Capitec. DM
Related Topics
Keywords
Related Stories
CONGRESS IN THE BALANCE: A blue tsunami, a tide, or chaos as usual — the US midterm election
With just hours to go before the American midterm election takes place, the day before South Africa’s own local election, control of both houses of the American Congress hangs in the balance.
DIVISIVE WORDS: ‘We never called for literal killing’ — Malema appeals for farm killings to stop.
EFF leader Julius Malema says the chant “Kill the boer, kill the farmer” was never meant literally and has appealed for farm killings to stop.
TRC ROULETTE : Victims’ families place key hidden evidence before Khampepe inquiry
A physical inspection of old lever arch files by the legal team representing the families of apartheid victims at the Khampepe Commission strengthens Anton Ackermann’s claim that a disputed 2006 memo was forged, reshaping the Khampepe inquiry into delayed apartheid prosecutions.
REAL ESTATE & GOVERNANCE: How SA property prices reflect municipal service delivery
South Africa’s property prices broadly track municipal performance, with Cape Town leading and Buffalo City lagging, but several metros challenge the pattern.
Top Stories
CONGRESS IN THE BALANCE: A blue tsunami, a tide, or chaos as usual — the US midterm election

'We've got big problems' - Hamilton says Ferrari need 'serious talks'

Detroit linebacker Campbell taken to hospital with neck injury
DIVISIVE WORDS: ‘We never called for literal killing’ — Malema appeals for farm killings to stop.

Antonelli becomes world champion as Verstappen wins in Mexico
TRC ROULETTE : Victims’ families place key hidden evidence before Khampepe inquiry
REAL ESTATE & GOVERNANCE: How SA property prices reflect municipal service delivery
LOCAL ELECTIONS 2026: Thirteen mayoral candidates, plenty of blame and a crowd of fed-up residents
Latest
CONGRESS IN THE BALANCE: A blue tsunami, a tide, or chaos as usual — the US midterm election
'We've got big problems' - Hamilton says Ferrari need 'serious talks'
Detroit linebacker Campbell taken to hospital with neck injury
DIVISIVE WORDS: ‘We never called for literal killing’ — Malema appeals for farm killings to stop.
Antonelli becomes world champion as Verstappen wins in Mexico
TRC ROULETTE : Victims’ families place key hidden evidence before Khampepe inquiry
REAL ESTATE & GOVERNANCE: How SA property prices reflect municipal service delivery
LOCAL ELECTIONS 2026: Thirteen mayoral candidates, plenty of blame and a crowd of fed-up residents